Collection performance can look very different depending on the KPI you choose. One dashboard may show dollars collected, while another focuses on recovery rate, aging buckets, days sales outstanding, or payment-plan performance.
The collection effectiveness index, usually shortened to CEI, adds another perspective: how much of the receivables available to collect during a period were actually converted into cash.
That makes the collection effectiveness index useful, but easy to misapply. CEI is fundamentally an accounts receivable measure. It can help creditor finance teams, credit and collections teams, first-party or early-out programs, and collection agencies with the right client data. It should not automatically replace third-party recovery or liquidation metrics.
What Is the Collection Effectiveness Index?
CEI measures the percentage of collectible accounts receivable converted into cash during a defined period. As a collection performance measure, CEI helps show how effectively an organization collected the receivables that were available during that period, with results closer to 100% generally indicating stronger collection effectiveness.
The metric adds context because accounts receivable changes throughout the month. New sales increase the balance, cash collection reduces it, and credits, disputes, write-offs, or other adjustments can change what remains open. The index uses beginning receivables, credit sales, the ending balance, and current balances to show how effectively the organization collected what was available.
The CEI Calculation
A common one-period CEI formula is:
CEI = [(Beginning Receivables + Credit Sales − Ending Total Receivables) ÷ (Beginning Receivables + Credit Sales − Ending Current Receivables)] × 100
The inputs are:
- Beginning receivables: total open receivables at the start of the period.
- Credit sales: new receivables created during the period.
- Ending total receivables: all open receivables at period end.
- Ending current receivables: the portion of ending receivables that is not yet due.
Oracle’s Collections Effectiveness Index documentation uses the same core components and connects CEI with current receivables and delinquency metrics.
A Simple CEI Example
Assume a creditor begins the month with $500,000 in beginning AR, generates $300,000 in monthly credit sales, ends with $350,000 in total open receivables, and has $200,000 in ending current AR.
[($500,000 + $300,000 − $350,000) ÷ ($500,000 + $300,000 − $200,000)] × 100 = 75%
The CEI score is 75%. That does not mean the collections team recovered 75% of every delinquent account ever assigned. It means the organization collected 75% of the receivables considered available under the formula during that period.
CEI vs. DSO: Different Questions, Better Together
Days sales outstanding, or DSO, estimates how long receivables remain outstanding relative to sales. DSO is useful for monitoring collection speed, working capital, and cash flow. CEI asks a different question: how completely did the organization collect what was available to collect?
The two metrics can move differently. DSO can shift with sales timing, while the collection effectiveness index separates current receivables from the pool considered collectible. Used together, CEI and DSO can give finance and AR teams a fuller view of financial health and cash flow.
Using aging reports to group open transactions into aging buckets gives teams another way to understand outstanding receivables, prioritize collection efforts, and refine collection strategies.
CEI vs. Recovery Rate and Liquidation Rate
This distinction matters for third-party collection agencies. The index relies on creditor-side accounts receivable inputs such as new receivables and current receivables. An agency recovery or liquidation rate usually compares cash recovered with a defined pool of placed debt.
Those measures answer different questions. A creditor may have a good collection effectiveness index overall while a specific agency placement performs poorly. An agency may produce strong results on delinquent accounts without having the creditor’s full sales data or current AR, which makes a true CEI calculation impossible.
That is why agencies should pair CEI with portfolio metrics rather than treating it as a universal score. Our guide to portfolio reporting by vintage explains how comparing placements at equivalent ages can reveal performance differences that a top-line CEI cannot.
What Can Move a CEI Score?
A lower index can reflect more than collector effort. Late payments may rise because payment terms changed. Delayed invoicing can distort the measurement period. Weak credit policies or overly generous credit limits can increase credit risk before the collections process begins. Disputes, bad debt, recalls, and write-offs can also affect interpretation.
Payment options matter because easier digital payment paths can improve cash flow, but the score alone will not explain why cash collection changed. When the metric moves, drill into payment history, customer segments, aging report data, delinquent accounts, and collection practices.
For creditor organizations, an ERP or accounts receivable automation system may supply some of these inputs. The important point is consistency: the same definitions and source systems should be used from period to period.
How Collection Agencies Can Use CEI in Client Reporting
Define the Data Scope
Confirm whether CEI comes from the creditor’s full accounts receivable ledger, an early-out population, or another defined pool. Do not mix placement balances with credit sales unless the methodology supports it.
Keep the Measurement Period Consistent
Monthly, quarterly, and annual CEI can all be useful, but comparisons should use consistent periods and definitions for beginning AR, current AR, and ending receivables.
Pair CEI With Agency KPIs
For third-party agencies, CEI becomes more useful when paired with recovery dollars, liquidation rate, contact outcomes, payment-plan performance, dispute aging, and portfolio age. Aktos’s guide to collection agency reporting dashboards explains why client reporting works better when performance measures connect to underlying account activity.
Document Policy and Portfolio Changes
Changes in credit policies, collection policies, payment terms, client recalls, write-offs, or portfolio mix can shift the result. Documenting those changes protects customer relationships by making the report easier to explain rather than leaving clients to guess at the cause.
How to Improve Collection Effectiveness Without Chasing the Metric
The most durable way to improve collection effectiveness is to improve the collections process itself. Start with clean invoicing and reliable account data. Review credit management and credit terms upstream. Use aging buckets to prioritize outstanding receivables, make payment options easy to use, and follow up consistently on broken arrangements.
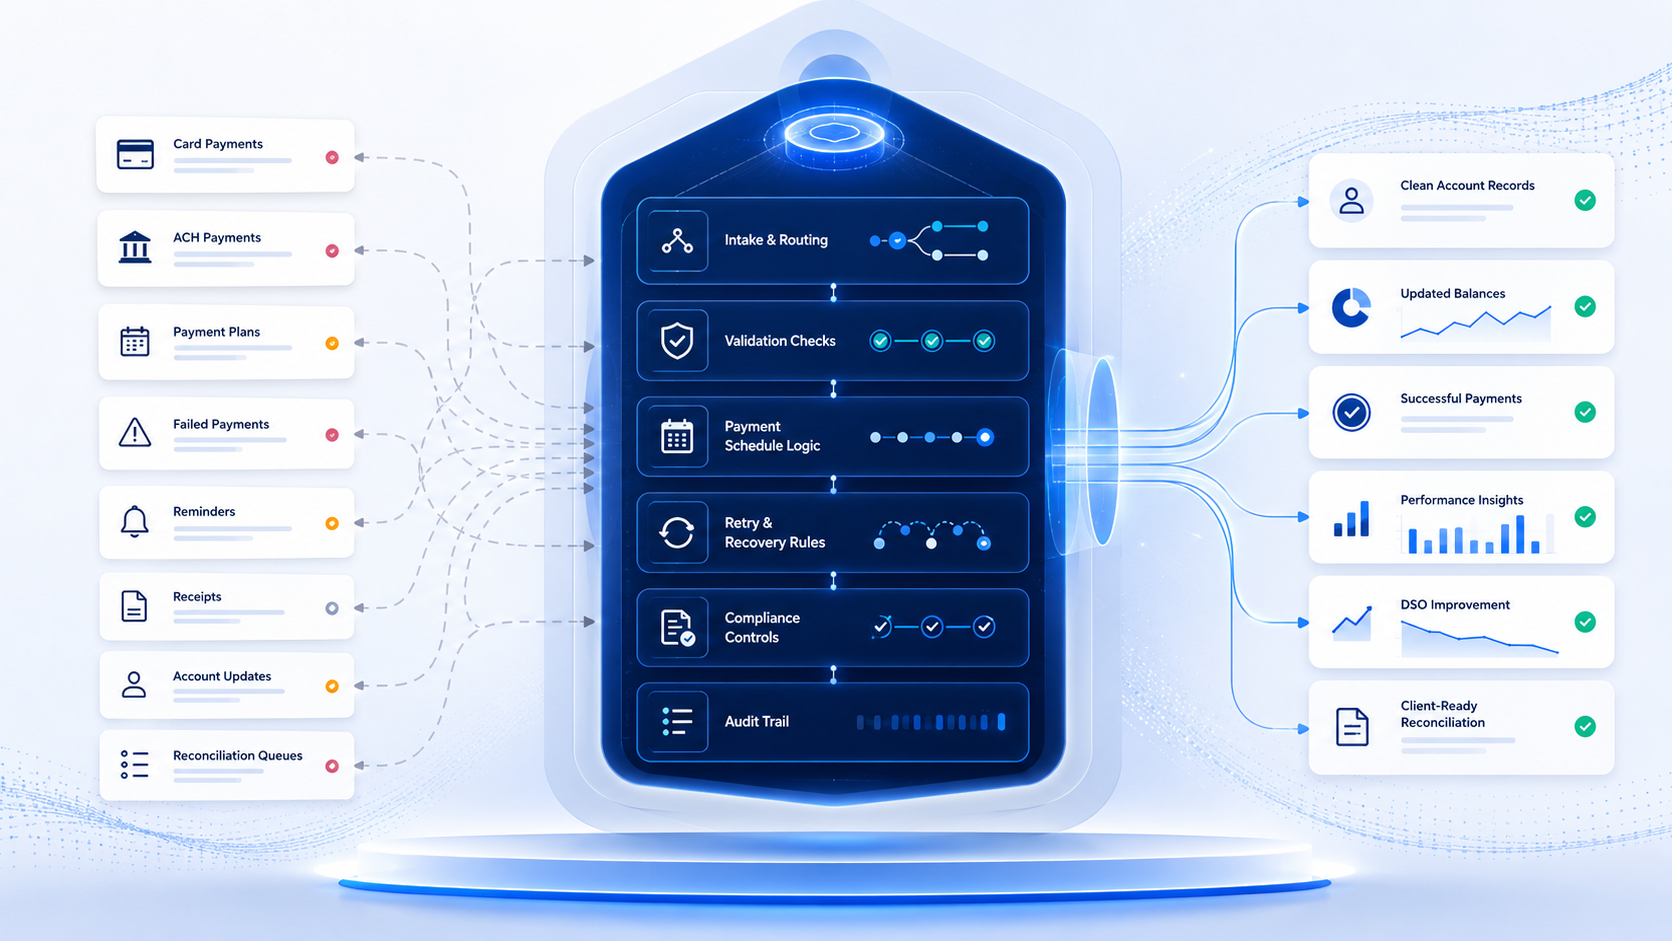
Accounts receivable automation can keep reminders, account status, and reporting synchronized. For agencies, debt collection payment automation can connect payment arrangements, failed-payment handling, posting, reconciliation, and client reporting.
Those improvements support more consistent receivables collection, greater efficiency, steadier cash flow, and long-term financial stability without turning the metric itself into the goal.
Final Thoughts: Use CEI for Context, Not as a Shortcut
The collection effectiveness index is a useful key performance indicator when the inputs are available and consistently defined. For creditors, CEI can show how effectively collectible receivables become cash. For agencies, it can add context in first-party, early-out, or client-reporting settings.
The best reporting model pairs the index with DSO, aging, recovery, liquidation, and portfolio metrics. At Aktos, we help agencies keep payments, account status, workflows, and reporting connected so performance changes can be traced back to the activity behind them.
FAQs
Q: What is a good collection effectiveness index?
A: A higher CEI generally indicates stronger collection effectiveness, with results closer to 100% showing that a larger share of collectible receivables was collected. The most useful benchmark is often a consistent internal trend over time.
Q: Is CEI the same as DSO?
A: No. DSO measures collection speed in days, while CEI measures how much of the receivables available for collection were actually collected. They are complementary metrics.
Q: Is CEI the same as recovery rate?
A: No. CEI uses beginning receivables, credit sales, ending total receivables, and ending current receivables. Recovery or liquidation rate usually compares cash recovered with a defined balance of placed debt.
Q: Can a third-party collection agency calculate CEI?
A: Yes, if it has the required receivables data and a clearly defined reporting scope. Many agencies will still find recovery, liquidation, aging, and vintage metrics more directly relevant to placed accounts.