A rigid script can fail when a consumer asks an unexpected question, forcing the collector to repeat irrelevant language or improvise a risky response.
A stronger debt collection call script works like a map, not a teleprompter. It identifies mandatory language, approved talking points, conversation branches, escalation rules, and documentation requirements. Collectors still use active listening and judgment within an approved structure.
Agencies should have qualified counsel review required disclosures, FDCPA guidelines, TCPA considerations, recording notices, and jurisdiction-specific language. Generic collection call script samples can illustrate structure, but they are not legal advice or a substitute for agency policy.
What Is a Debt Collection Call Script Framework?
A framework separates four kinds of guidance:
- Mandatory language: Exact disclosures or notices used under approved conditions.
- Approved talking points: Explanations collectors can adapt without changing the meaning.
- Collector judgment: Questions, tone, pacing, and payment plan options permitted by policy.
- Supervisor actions: Disputes, complaints, exceptions, and sensitive escalations.
This makes debt collection call scripts easier to train and update while letting a debt collection agency maintain client-specific paths without forcing collection agents to memorize every variation.
Before the Call: Give Collectors the Right Context
Before dialing, collectors should see identifiers, account status, original creditor, placement details, payment history, prior outcomes, any payment arrangement, disputes, complaints, cease requests, consent preferences, client instructions, and documents.
That context matters whether the account involves a credit card, an overdue invoice, an outstanding debt, or another obligation. Unlike AR teams following up on accounts receivable, third-party debt collectors must also follow agency workflows, client rules, and the Fair Debt Collection Practices Act.
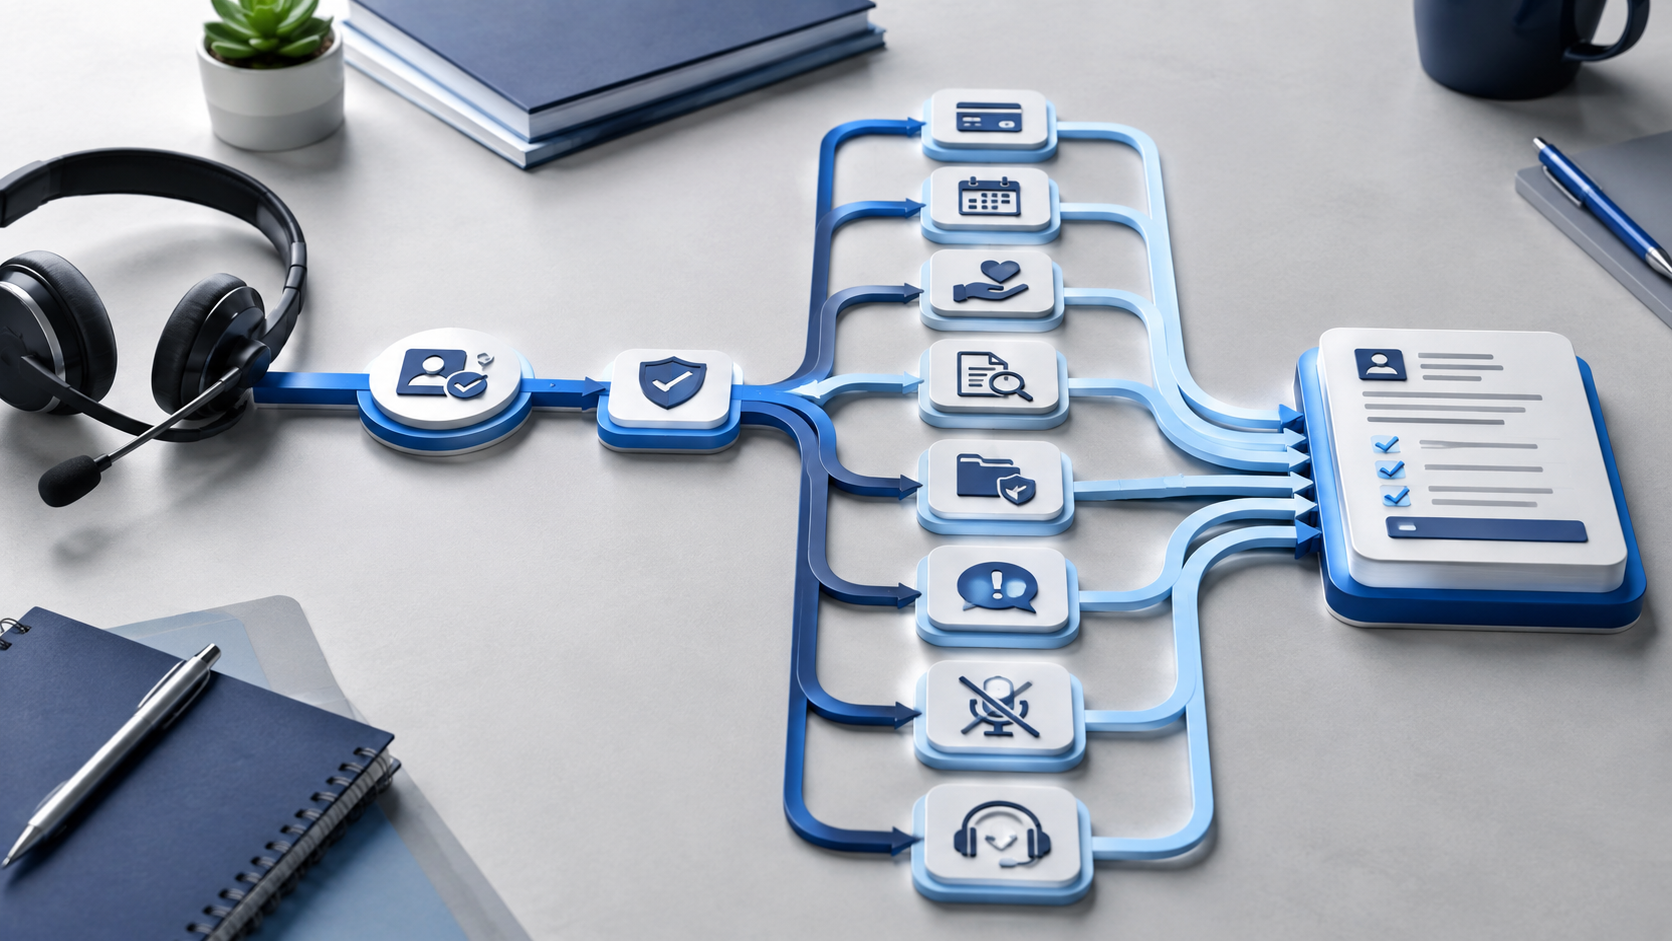
The Core Debt Collection Call Script Flow
1. Opening and Right Party Contact
Confirm right party contact before discussing the account. If someone else answers, do not reveal the creditor, outstanding balance, amount due, or purpose of the call. Provide only approved callback information.
If voicemail is permitted, use counsel-approved language. Regulation F defines a narrow limited-content message, so agencies should align voicemail procedures with the CFPB’s limited-content message requirements.
2. Identity Verification and Disclosures
Use the approved verification steps before sharing account information. Include branches for a consumer who refuses verification, cannot complete it, or says the number is wrong.
After verification, deliver disclosures at the approved stage. Keep exact language distinct from flexible guidance. Debt collectors should not paraphrase mandatory wording. Updated FDCPA guidelines should be version-controlled and acknowledged.
3. Explain the Purpose and Confirm Details
State the purpose professionally, then invite a question. Explain the outstanding balance from the system. For questions about the original creditor, overdue balance, past due balance, fees, or statements, use documented facts.
Collectors should not speculate about a credit score, threaten credit consequences, or guess when documentation is missing. The FDCPA prohibits false or misleading representations, making accurate account context as important as good delivery.
Conversation Branches for Common Outcomes
The Consumer Can Pay in Full
Confirm the amount due, payment date, and permitted method. Explain the authorization process for ACH or another approved option, provide confirmation, and document the result. If the consumer offers only a partial payment, move to the appropriate branch.
The Consumer Needs a Payment Plan
Ask only what is needed to establish an affordable schedule. Present approved installment plans or payment plan options, then confirm amount, frequency, dates, method, and failed-payment consequences.
A payment plan should be sustainable. For cash flow issues, a temporary cash flow problem, or financial hardship, avoid pressure, route exceptions, and record the payment arrangement and any partial payment.
The Consumer Questions or Disputes the Debt
Identify the concern, whether it be balance, creditor, payment history, identity, service, or fee, and assign any needed research with an owner and deadline.
When the consumer disputes the account, stop the normal payment discussion and enter the approved dispute workflow. Record the consumer’s words, update the status, and route supporting documents. Debt recovery should not continue on autopilot while a dispute requires review.
The Consumer Makes a Complaint or Cease Request
A complaint is not a routine objection. Listen, capture the requested resolution, and escalate according to severity and policy.
For a no-contact request, clarify whether it concerns one channel or broader communication, then record it immediately. The CFPB’s Regulation F communication rules address inconvenient communications, certain cease notices, third-party communications, and electronic opt-outs. Trigger the approved suppression or legal-review workflow rather than interpreting the request independently.
The Consumer Requests a Supervisor
Use a warm transfer when possible. Give the receiving person the account, request, key statements, and actions already taken before connecting the consumer. This reduces repetition and protects customer relationships during difficult calls.
How to Close and Document the Call
Every close should confirm the action, payment amount and date, follow-up, permitted channel, next contact, and callback information.
Call notes should capture right-party and verification results, disclosures delivered, questions, objections, arrangement details, disputes, complaints, communication requests, escalation destination, follow-up owner, deadline, and final disposition code.
Structured fields improve reporting and help managers compare recovery rates, repeat calls, kept promises, and quality exceptions.
Coach the Decision Tree, Not Robotic Wording
Teach collectors to recognize the active branch and switch when new information changes the call. Review missed questions, weak transitions, incomplete notes, and routing.
A useful scorecard can track right-party contact rate, arrangement conversion, kept-promise rate, first-call resolution, dispute-routing accuracy, note completeness, repeat-call rate, and call duration by outcome. Quality assurance inside collection software can connect those measures to coaching actions.
Collection call script samples work best in role-play: one cooperative consumer, one hardship case, one balance question, and one escalating complaint. The goal is consistent behavior, not identical sentences. Reliable debt collection call scripts standardize decisions without flattening tone.
How AI Phone Agents Fit the Framework
An AI phone agent should use approved conversation logic, limited account data, defined transfer conditions, and logged summaries, dispositions, and next actions.
Keep human review available for financial hardship, disputes, complaints, unusual questions, and sensitive escalations. Aktos supports inbound payments, payment plans, settlements, debt details, disputes, and verification with logged summaries.
For outbound artificial-voice calls, agencies should have counsel review TCPA requirements and consent procedures. Aktos’s AI phone agent compliance guide outlines additional operational considerations, and the FCC has confirmed that AI-generated voices fall within TCPA rules for artificial or prerecorded voices. A hybrid debt collection workforce is strongest when automation handles predictable paths and people handle judgment-intensive work.
Final Thoughts: Build a Framework Collectors Can Navigate
Reliable debt collection call scripts reduce improvisation without eliminating empathy by connecting approved language, account context, workflows, escalations, warm transfers, notes, and reporting.
Aktos brings those elements into one modern collection platform, helping agencies route conversations, document outcomes, and support human or AI-assisted calls. See how Aktos can help your team build more consistent call workflows by booking a demo.
FAQs
Q: Should collectors read a debt collection call script word for word?
A: Only language designated by counsel or policy as mandatory should be read exactly. The rest should guide questions, transitions, explanations, and escalation decisions.
Q: What should happen when a consumer disputes the account?
A: Leave the normal payment branch, document the dispute accurately, update the account, and follow the agency’s approved dispute process.
Q: How should a collector handle a cease request?
A: Document it immediately, clarify the applicable channel when appropriate, and trigger the approved suppression or legal-review workflow.
Q: What is a warm transfer in debt collection?
A: A warm transfer occurs when the first collector or AI agent gives the receiving person the account context before connecting the consumer.