The Mini-Miranda is short. Operationalizing it across hundreds or thousands of consumer interactions is not.
For third-party debt collectors, the core federal requirement comes from the Fair Debt Collection Practices Act and Regulation F. In an initial communication with a consumer, the collector must disclose that the debt collector is attempting to collect a debt and that information obtained will be used for that purpose. In subsequent communications, the collector must disclose that the communication is from a debt collector. The CFPB’s Regulation F guidance on required disclosures provides the federal framework agencies should use when building these requirements into their workflows.
Agencies call this the Mini-Miranda, Mini-Miranda warning, or mini Miranda statement. The challenge is delivering approved language at the right time without third-party disclosure, inconsistent scripting, or weak documentation.
This article is practical guidance, not legal advice. Agencies should have qualified counsel approve scripts and state-specific variations.
What the Mini-Miranda Means Operationally
The Mini-Miranda is not a criminal Miranda warning, and the phrase mini Miranda rights can be misleading. It does not create a separate set of consumer rights; it is an industry label for required debt-collection disclosures under federal law.
For the agency, the requirement must become workflow logic. The system should know whether an interaction is the initial contact, whether prior communication occurred, which script applies, and what evidence to retain.
The Federal Trade Commission's FDCPA text also shows why accurate disclosure matters. The FDCPA prohibits false or misleading representations and addresses civil liability for violations. Depending on the facts, litigation can involve actual damages, statutory damages, and attorney fees. Agencies should work with counsel rather than treating a script as a complete compliance program.
Build Approved Disclosure Language
Start with counsel-reviewed language and a controlled mini-Miranda script. Do not let every collector rewrite the disclosure in their own style.
Maintain the approved wording in a central script library, document when it changes, and define any client, jurisdiction, or account-specific variations. If the agency collects for multiple creditors or debt buyers, even where legacy systems label consumers as debtors, the script should pull the correct agency and account context without unnecessary information.
The point is repeatability. A supervisor should be able to answer: Which mini-Miranda disclosures were approved on the date of this call? Which version did the collector or AI use? Was it the correct version for this portfolio?
Identity Verification Comes Before Debt Details
Agencies need to avoid conveying consumer debt information to the wrong person. Before discussing a balance, original creditor, payment history, dispute, or other details, the workflow should follow identity-verification steps based on agency policy and counsel's guidance.
If verification fails, the collector should move to the approved non-disclosing path rather than improvising. The CFPB's definition of a communication is broad: it includes conveying information regarding a debt directly or indirectly through any medium. Its current Regulation F definitions are useful when designing call and voicemail workflows.
Verification and the Mini-Miranda solve different problems. Verification helps control who receives debt information; the disclosure tells the consumer the nature of the collection communication as required by the FDCPA.
Operationalizing Disclosures on Human Collection Calls
Human collectors need more than training slides. Put the approved language inside the collection workflow.
Collector screens can prompt the Mini-Miranda warning at the appropriate point, show whether identity has been verified, and record the disposition of the interaction. Supervisors should review collection calls for disclosure delivery, verification, accuracy, dispute recognition, and documentation.
Training should cover edge cases: interruptions, callbacks after voicemail, wrong-party claims, and a consumer who wants to dispute the debt immediately.
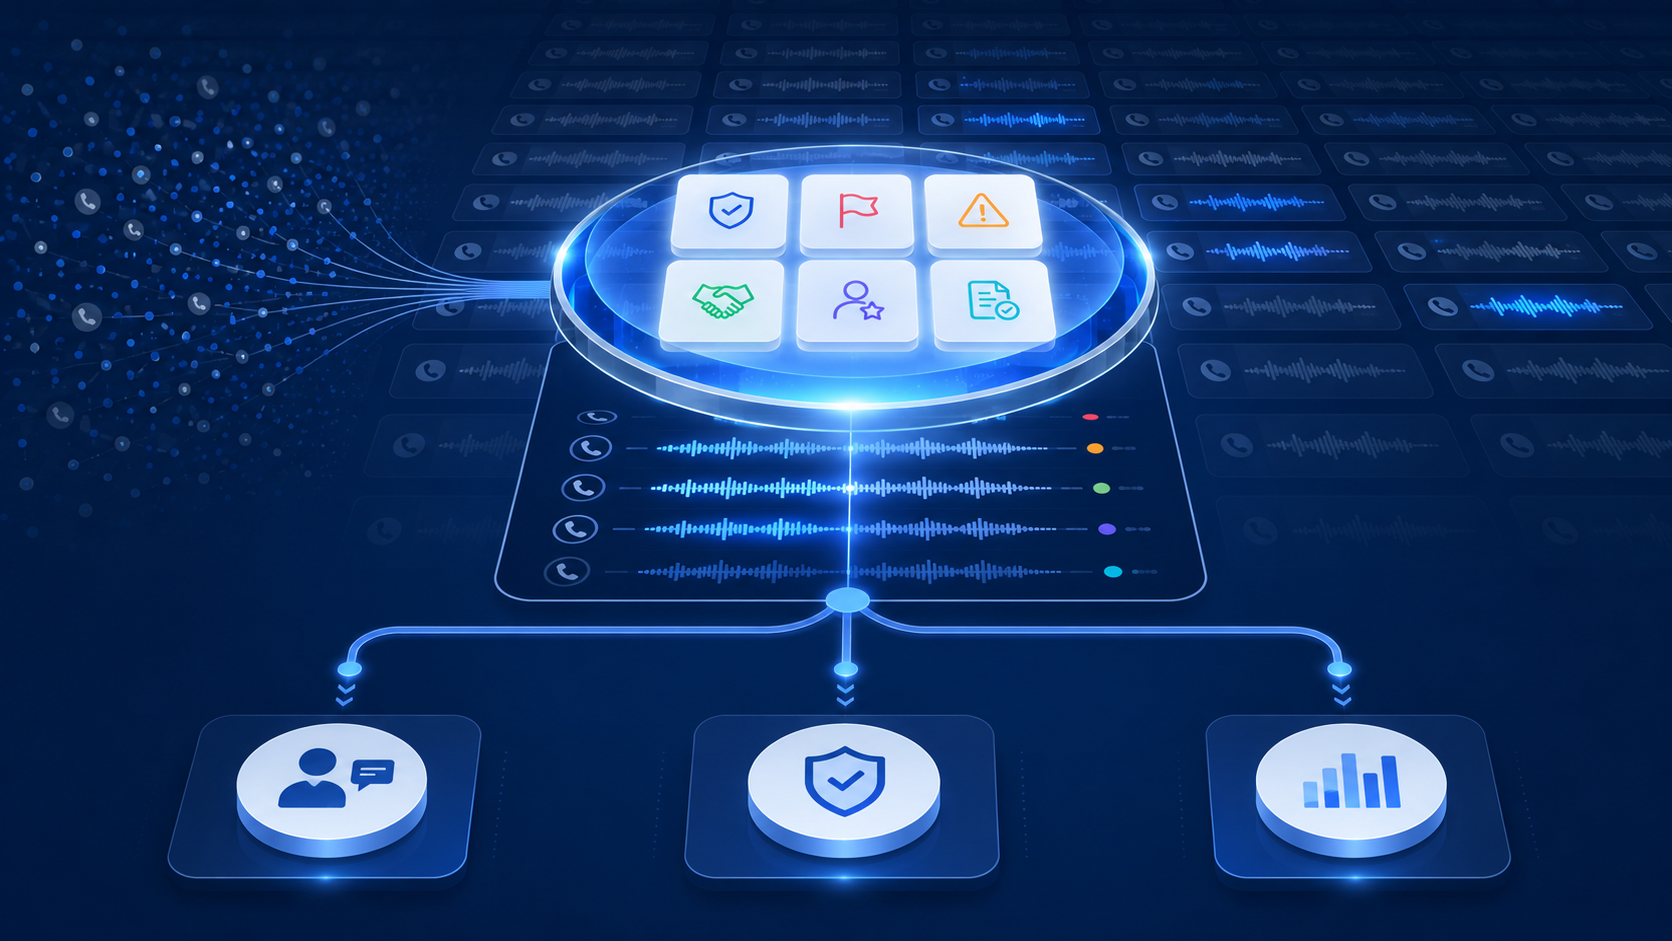
With Aktos, you can build a more systematic debt collection quality assurance process by bringing call records, transcript reviews, disclosure checks, and workflow context into the same place.
Operationalizing Disclosures With AI Agents
AI does not eliminate the requirement for approved language; it increases the need for controlled trigger logic.
An AI agent should know when verification is complete, when the Mini-Miranda must be delivered, which wording is approved, and when to transfer the interaction to a human. The conversation log should record the script version, disclosure event, account context, and downstream action.
For enterprise agencies, test interruptions, ambiguous answers, failed verification, multiple accounts, disputes, hardship, and supervisor requests. The AI should not invent FDCPA explanations, threaten legal action, or assume a statute of limitations. Sensitive legal questions belong in the approved escalation process.
Mini-Miranda QA Checklist
A QA review asks whether the consumer was verified before debt details were discussed; whether the required disclosure and approved wording were used; whether the interaction was logged; and whether the collector or AI followed the correct next step.
The checklist should also verify that account notes identify the creditor accurately, preserve any dispute or complaint, and stay consistent with the validation notice and other communications. With Aktos, you can manage validation notices as part of the broader compliance workflow while keeping them distinct from Mini-Miranda requirements.
Limited-Content Messages Are Different
Do not copy live-call disclosure logic directly into voicemail.
Regulation F defines a limited-content message as a voicemail containing only certain permitted information. Because it does not convey details about the debt, it is treated as an attempt to communicate rather than a full communication. That means the usual debt-collection disclosures do not need to be included in the message.
That distinction matters. Adding language like “this is a debt collector” or other debt details can take a voicemail outside the limited-content-message framework. If you want to go deeper, our guide on leaving voicemails in debt collection breaks down how to handle these messages in practice.
Build separate voicemail rules instead of assuming the same mini miranda script belongs everywhere.
Make Compliance Part of the Workflow
Training alone is fragile. A modern debt collection agency should reinforce approved disclosures with system prompts, communication rules, audit logs, script versioning, exception handling, and corrective-action workflows.
This matters even more across large teams, multiple clients, and channels. A creditor may have portfolio-specific instructions, while federal law and state requirements can add another layer. The Federal Trade Commission, CFPB, and state regulators can update guidance or enforcement priorities, so agencies need a process for reviewing policy changes and updating software rules.
Good consumer protection operations also preserve evidence. If a complaint alleges FDCPA violations, the agency should be able to retrieve the interaction, approved script, account state, verification result, and follow-up actions without reconstructing the story from memory.
Final Thoughts: Turn the Disclosure Into a Control
The Mini-Miranda is easy to memorize and easy to operationalize poorly. The stronger approach is to treat it as a controlled event inside the collection workflow: approved language, correct timing, identity safeguards, documentation, QA, and escalation.
Aktos brings call records, workflow automation, AI agents, audit trails, and account context into one modern collection platform so agencies can make compliance evidence easier to manage consistently. Our technology does not replace legal review, but it can make a counsel-approved process far easier to execute at scale.
FAQs
Q: What is a Mini-Miranda in debt collection?
A: Mini-Miranda is the industry term for disclosures required under the FDCPA and Regulation F. In the initial communication, a debt collector must state that it is attempting to collect a debt and that information obtained will be used for that purpose; subsequent communications require disclosure that the communication is from a debt collector.
Q: When should collectors deliver the Mini-Miranda?
A: The federal disclosure rules distinguish initial and subsequent communications. Agencies should map those triggers into their workflows and have counsel approve the exact language and sequencing used for their call, written, and digital processes.
Q: Do AI collection agents need approved disclosures?
A: Yes. If an AI agent is conducting a communication subject to the disclosure requirement, the agency should use counsel-approved language and controlled trigger logic just as it would for a human collector, while also preserving logs for QA and audit review.
Q: How are limited-content messages different?
A: A compliant limited-content voicemail under Regulation F is an attempt to communicate but not a communication that conveys debt information. Because of that distinction, the normal § 1006.18(e) disclosure is not required inside the limited-content message itself.