A collector can only work so many accounts in a day. The operational question is not whether a collection agency has enough accounts to call. It is whether the right accounts are reaching the right person, channel, or workflow at the right time.
That is where a debt collection scoring model becomes useful. A scoring model can rank or group collection accounts using signals such as payment history, placement age, balance, contactability, prior responses, and workflow status. Done well, collection scoring creates a more deliberate order of work than "oldest first" or "highest balance first." Done poorly, it becomes a black box that collectors do not trust.
What Is a Debt Collection Scoring Model?
A debt collection scoring model assigns an account a score, tier, or priority based on selected characteristics and historical data. The result can influence which queue receives the account, whether an automated sequence starts, whether a collector reviews it, or whether it pauses for more information.
This is different from a traditional credit scoring model used to estimate creditworthiness before lending. In debt collection, the model is usually trying to support debt recovery decisions after an account is already delinquent or placed with an agency.
Two accounts with the same balance can deserve different treatment if one has verified contact data and a recent payment while the other has missed payments, incomplete data, or an active dispute.
Start With the Decision the Score Will Change
Before selecting variables or machine learning methods, define the decision the score should improve. Common use cases include prioritizing collections for collector queues, deciding which accounts enter an outreach sequence, identifying accounts that need enrichment, routing high-risk accounts to senior staff, or sequencing follow-up after a broken promise or failed payment plan.
Our guide to queue management software shows the practical end state: eligibility first, then priority, routing, exception handling, and measurable queue health.
Inputs That Make Collection Scoring More Useful
Payment History and Account Economics
Prior payments, failed transactions, active payment plans, settlement activity, and broken promises can all change the recovery strategy. Balance matters too, but a higher balance does not automatically mean a better use of collector time.
Recovery rates should be reviewed by score band so the agency can see whether the ranking actually predicts better outcomes.
Age, Placement Timing, and Contactability
Placement age and account age are not always the same. A receivable may be old when the agency receives it, while another account may have been in the agency's workflow for months. Keeping both timelines visible can prevent simplistic assumptions about late payments.
Contactability matters too: verified phone or email data, recent responses, returned mail, and wrong-party contacts can change whether the next action is likely to be productive.
Credit History and External Data
Some organizations may use credit report information, credit history, or other permitted external data as part of segmentation. That area requires careful governance. The Fair Credit Reporting Act places obligations around consumer-report information and furnishing, while the CFPB's Regulation F governs covered debt collection activity. Agencies should work with qualified counsel before using consumer-report data in collection strategies.
Rule-Based Scoring vs. Predictive Scoring
Not every debt collection agency needs machine learning on day one.
A rule-based scoring model is often easier to explain and deploy. An agency might add priority for a recent placement, verified contact information, or a successful prior payment, while lowering priority when data is missing or repeated attempts have failed. Rules are transparent, easy to test, and useful when historical data is limited.
A predictive model can go further by identifying patterns across past outcomes. Predictive analytics can estimate the likelihood of contact, payment, cure, or another operational event. Machine learning can also combine variables in ways that are difficult to capture in a hand-built formula.
One common statistical approach is logistic regression. Logistic regression estimates the probability of an outcome from a set of inputs, which can make it useful for binary events such as whether an account pays within a defined period. Logistic regression is often easier to explain than more complex machine learning methods because teams can review which variables are influencing the result. Even then, logistic regression should be validated on current portfolio data rather than assumed to work across every client.
Keep Eligibility Separate From Opportunity Scoring
A high score does not mean an account is eligible for every action.
The FDCPA, client rules, disputes, cease requests, legal holds, communication restrictions, and other controls should sit above the scoring layer. The FTC's FDCPA resource is a useful federal reference, but agencies should also account for state law and qualified counsel's guidance.
Think of risk scoring or collection scoring as a prioritization layer inside approved workflow controls. An account can have a strong recovery score and still be routed to review rather than outreach.
Turn Scores Into Dynamic Queues
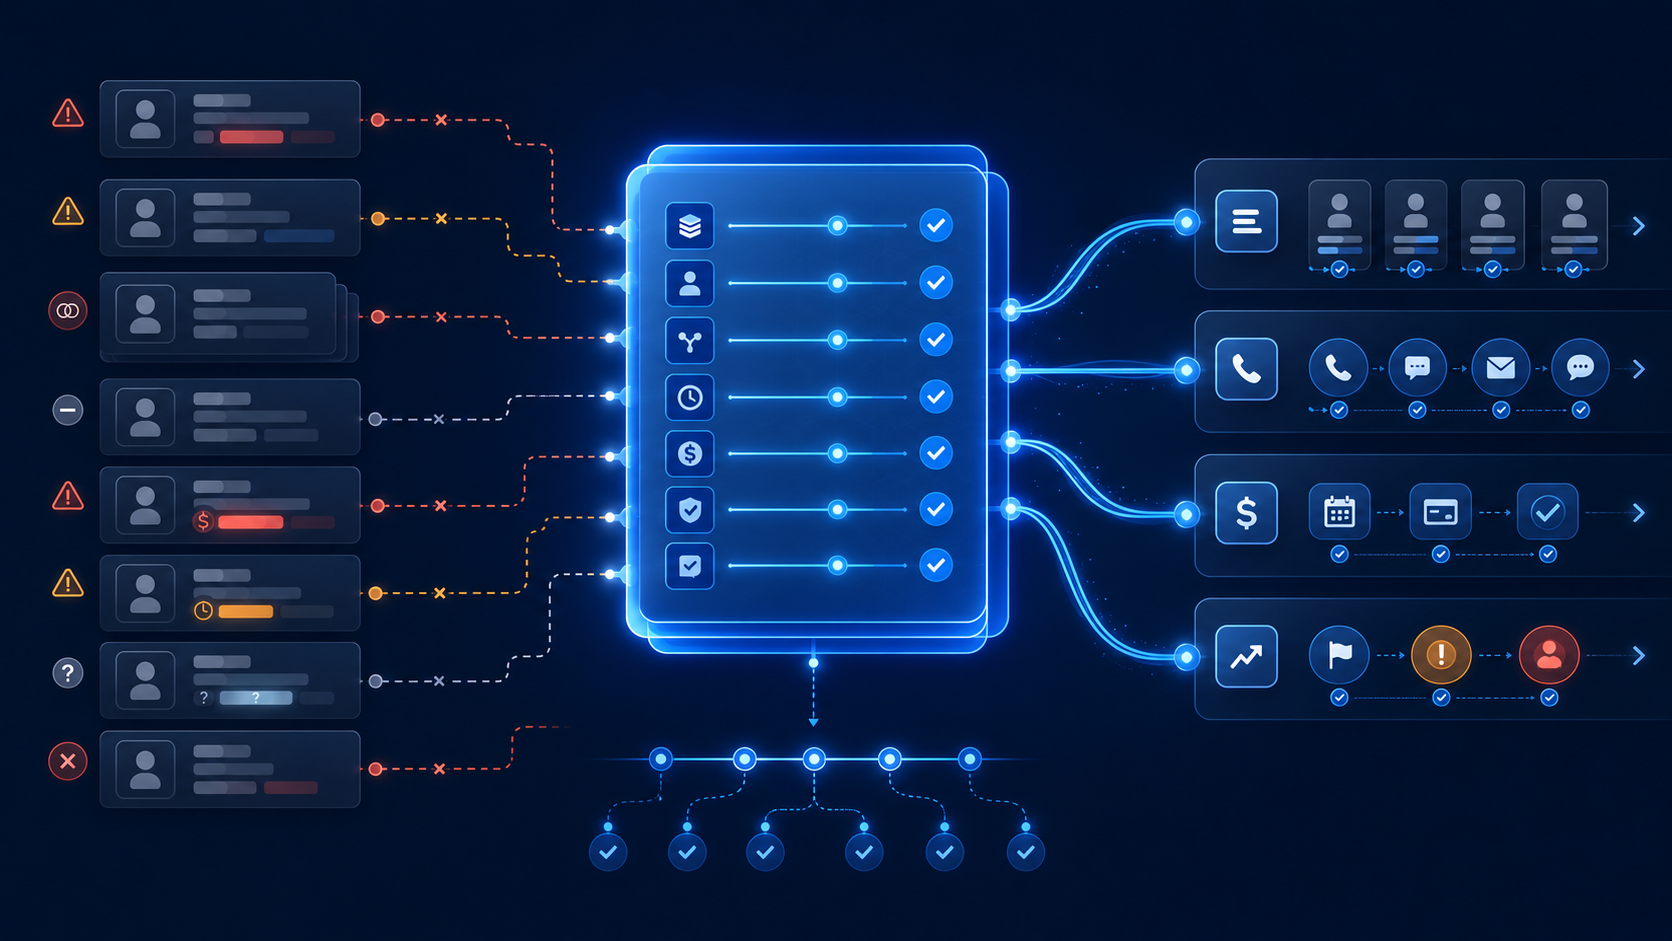
Collection scoring becomes valuable when it changes daily work. A practical flow looks like this: a new placement passes intake validation, the system calculates a priority tier, eligibility rules determine allowed actions, and the account enters the right collector queue or automated workflow. When a payment, dispute, response, failed contact, or new data point changes the account, the routing can update.
This is also where clean integrations matter. If payment data sits in one system, communication outcomes in another, and client updates arrive in an ERP or separate file, the predictive model is working from partial context. We explain the connection between data quality and scoring in How Clean Data Improves Debt Collection AI.
Measure Whether the Model Improves Operations
A scoring model should be reviewed like an operating decision, not a one-time data science project. Compare recovery rates, right-party contact, payment plan performance, collector time, override rates, and stranded-account volume by score band or queue.
For creditor-side finance teams, metrics such as DSO or days sales outstanding may matter. For third-party agencies, the more useful measures are usually recovery, liquidation, contact, payment performance, and operational capacity. The point is to measure whether the score improves the next action.
Frequent overrides can signal stale data or a weak scoring model. To prioritize collections well, debt collectors should segment by consumer behavior: fintech and credit card portfolios may need different collection strategies across the debt collection industry. Compare recovery rates rather than assuming one universal score fits every portfolio.
What Modern Debt Collection Software Should Support
Debt collection software should connect scoring to account state, payment history, client rules, communication history, and current eligibility. It should also preserve why an account was prioritized, allow controlled overrides, and show managers how each queue is performing.
At Aktos, we support this operating model through configurable workflows, segmentation, automation, integrated account data, and collector queues. Instead of treating collection scoring as a separate report, agencies can connect priority decisions to the workflow itself. For a broader look at the automation layer, see Debt Collection Automation That Scales.
Final Thoughts: A Better Score Should Create a Better Next Action
The point of a debt collection scoring model is not to assign every consumer a mysterious number. It is to help a collection agency decide what should happen next.
Start with the decision, use data you trust, keep eligibility separate from opportunity scoring, and measure whether the model improves debt recovery.
FAQs
Q: What is collection scoring in debt collection?
A: Collection scoring ranks accounts by expected opportunity, urgency, contactability, or complexity so the agency can prioritize collector work, automation, enrichment, or review.
Q: Is a debt collection scoring model the same as a credit scoring model?
A: No. A credit scoring model is generally used in lending and credit decisions, while a debt collection scoring model is used after delinquency or placement to support collection strategy and prioritization.
Q: Does machine learning always outperform rule-based scoring?
A: No. Machine learning can uncover useful patterns, but transparent rules may be better when data is limited or portfolios change often.
Q: Can scoring help reduce DSO?
A: It can support faster prioritization and payment follow-up, which may influence DSO in creditor-side accounts receivable operations. Third-party agencies should also track recovery-specific metrics such as liquidation, contact, and payment performance.