A manager changes a rule so accounts with a missed installment receive payment reminders sooner. It looks like a small adjustment, but the same rule may also affect consumers with disputes, recent payments, or communication opt-outs. Debt recovery automation can multiply a good decision across thousands of accounts, and multiply a poorly tested decision just as quickly. Release discipline matters as much as the automation itself.
For agencies using automated debt collection software, every change should preserve account context and regulatory compliance. Debt collection platforms need an explainable debt collection process, whether staff or AI agents initiate the next action. This guide focuses on testing automated workflows before deployment, not assuming a faster rule will improve recovery rates or consumer outcomes.
Map Rule Changes and Dependent Collection Workflows
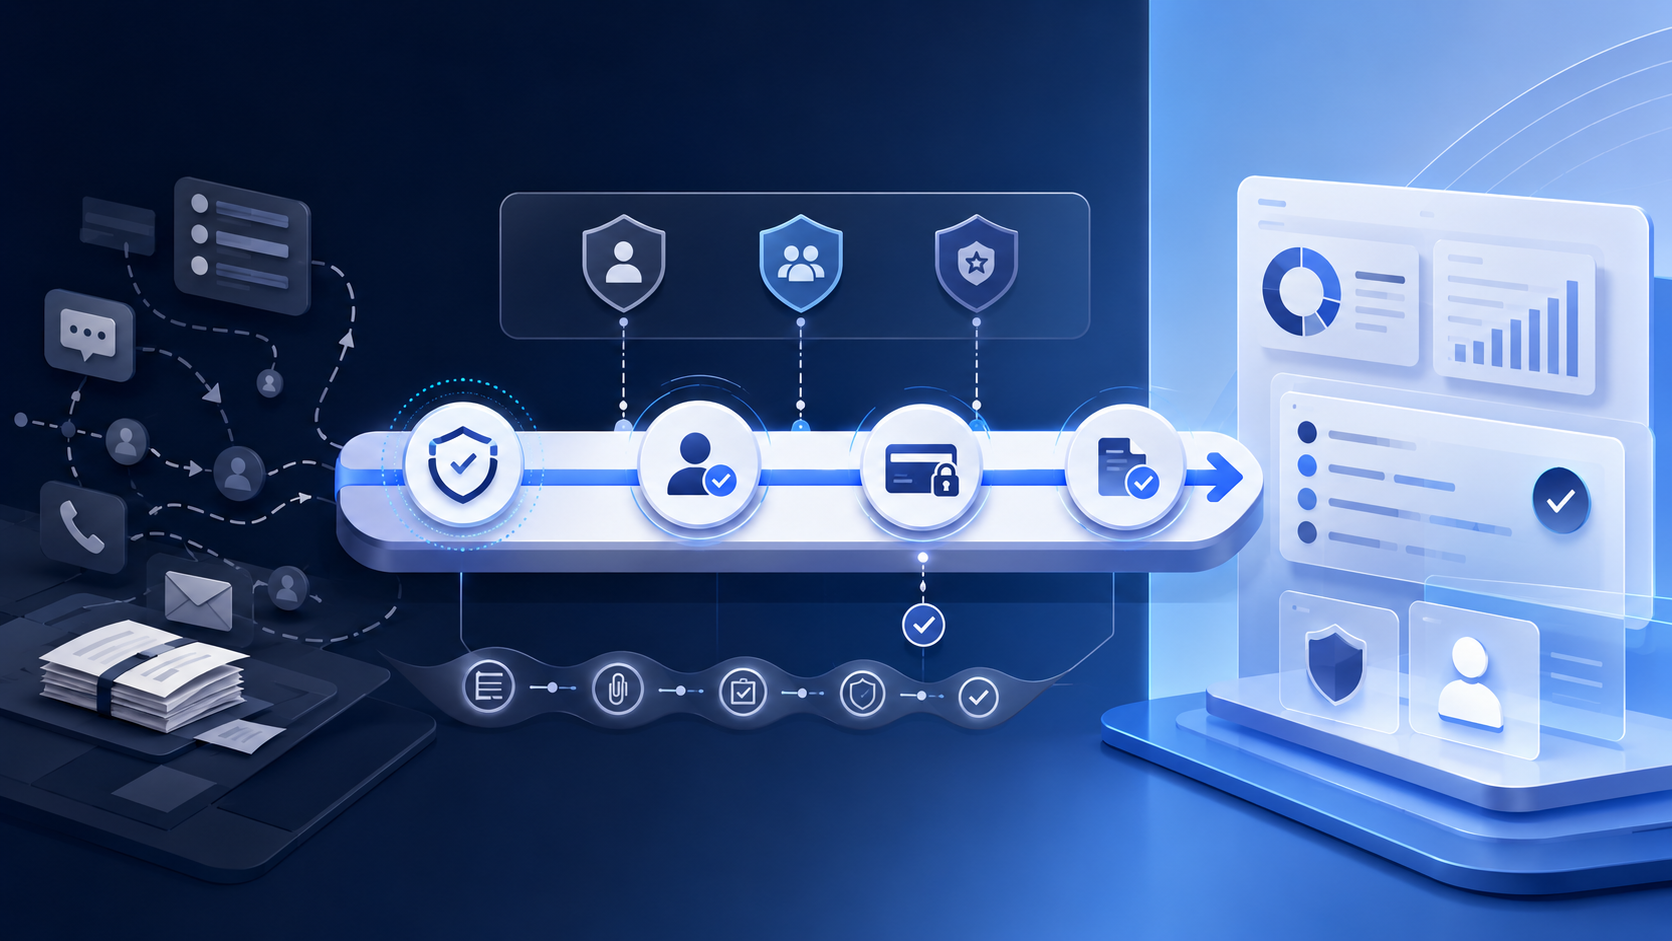
Write a change request that states the trigger, affected portfolio, account states, message channels, intended outcome, and conditions that should stop the action. Compare the proposed rule with client restrictions, FDCPA controls, Regulation F requirements, and applicable TCPA rules. A reminder rule may intersect with payment posting, promises to pay, consent status, account recalls, and disputes.
Map debt collection software dependencies before touching production. Determine whether the change affects only one sequence or shared logic used by several clients. Record current configuration, rule ownership, and an explicit rollback version. If a no-code editor makes changes easy, governance becomes more important, not less, because operational teams can deploy without a software release cycle. The approved version should include the original trigger and every dependent suppression rule. Record who tested each scenario and which account states were excluded. When a shared condition changes, recheck the other client workflows that use it, rather than assuming a successful test of one sequence proves every related journey.
Map the full debt recovery process. A collection CRM, dialer, payment portals, and self-service portals may respond to the same event. Check how payment processing and cash applications update an account before automated communications resume. A missed installment, overdue payments, or changed payment arrangements should trigger only the approved action, not conflicting reminders across disconnected tools.
Apply enterprise automation controls before the rule is edited, identifying shared conditions, account restrictions, and downstream dependencies that could turn a local change into unexpected activity across other client portfolios.
Test Payments, Disputes, Opt-Outs, and Conflicting Rules
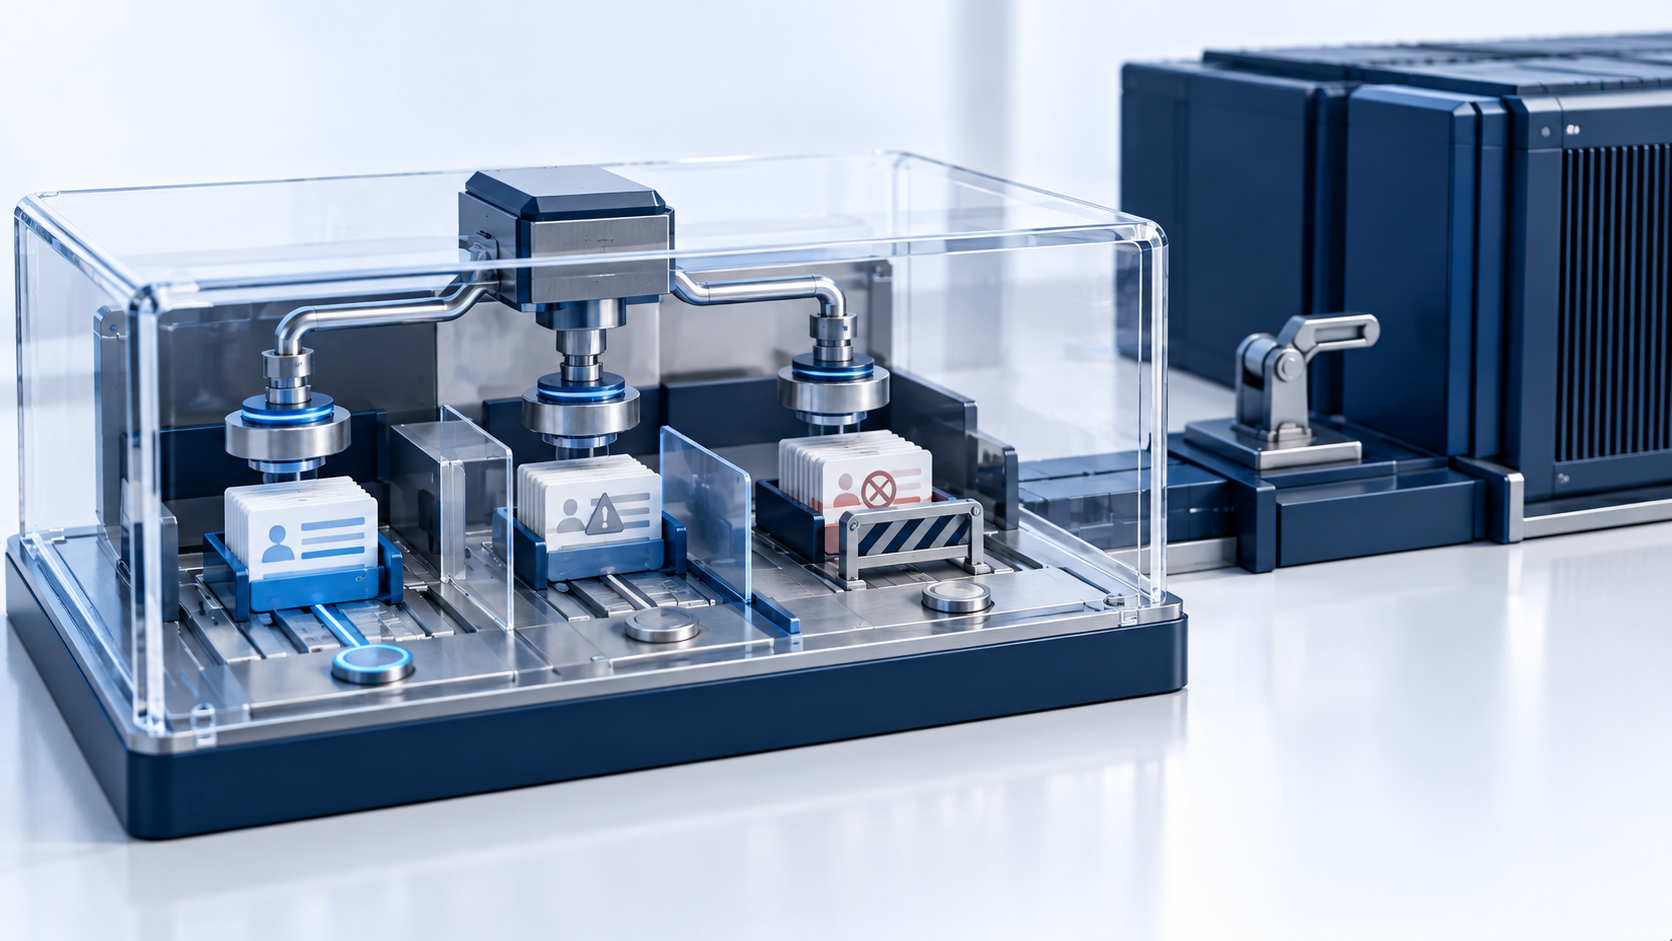
Use a sandbox or a non-sending simulation with representative test accounts. Include a normal eligible account, a recent payment, a failed payment, an active dispute, a cease request, an invalid contact, a recalled account, and a consumer in a restricted time zone. Specify expected outcomes before running the test. A test passes only when both the intended action occurs and prohibited or unnecessary actions do not.
Regression tests should revisit unrelated journeys that depend on the same event. For example, changing a payment-failure trigger must not accidentally reactivate a resolved account. Evaluate duplicate events and delayed integration messages. Predictive analytics or machine learning can influence prioritization, but testing should still establish how the system behaves when the output changes or is unavailable.
Test artificial intelligence separately from deterministic rules. Conversational AI and chatbots using NLP must handle disputes, repayment plans, and requests for a person appropriately. AI agents interpreting debtor behavior need clear escalation boundaries. Account prioritization for high-risk accounts should remain reviewable; an intelligent automation label does not establish that restricted accounts are excluded.
Test automated collection guardrails against prohibited actions as well as intended outcomes, so a successful reminder test cannot conceal a dispute hold, communication restriction, or payment event that was ignored.
Pilot Automation Changes With Clear Rollback Triggers
Require approval from the process owner and compliance reviewer where appropriate. Launch to a constrained internal test segment or approved pilot before a broader rollout. Record the change version, approvers, test results, and deployment time. Set clear stop conditions such as unexpected outbound volume, restriction conflicts, rising error rates, or mismatches between payment and outreach status.
Monitor the first production events rather than relying on an end-of-month report. A rollback should restore the previous approved behavior and account for messages already queued with external vendors. Post-launch review should compare intended and actual outcomes, documenting improvements that can be used in the next release. Successful debt recovery automation is repeatable and inspectable, not simply fast.
A creditor's AR platform may send invoice balances and payment updates to an agency. Test how those updates affect dispute holds, collection balances, and communication restrictions. Verify the event format, delivery timing, and account mapping before relying on the integration.
Make collection software quality assurance part of post-release review, comparing sampled account outcomes with approved scenarios and feeding each confirmed exception back into the next version of the test plan.
Assign Release Ownership and Verify Account Outcomes
Assign one owner for collections automation across operations, compliance, and technology. Define what the software may change automatically, which processors send payment updates, and who approves exceptions. For creditor-system feeds, document who maintains field mappings and investigates failed or conflicting updates.
Test representative accounts with active disputes, validation notices, payments in progress, and missing information. Include a delayed payment update and a dialer queue created before a restriction arrived. Confirm that new data changes the balance or status as expected and that restricted outreach remains blocked.
Create a test matrix for every changed automation rule. An eligible account should receive the intended payment reminder; an account with a dispute, cease request, recent payment, or inactive status should not. Test duplicate webhook delivery, delayed cash application, and conflicting client rules before release. Record the rule version, expected result, reviewer, and rollback trigger. If any restricted account becomes eligible for outreach, stop deployment until the cause is resolved.
Measure restriction conflicts, duplicate activity, unresolved exceptions, and incorrect status changes. Keep an audit trail showing which rule version acted. Separate source-system delivery failures from agency processing failures and assign someone to investigate each.
Review Automation Approvals, Test Evidence, and Vendor Events
Require approval of the rule version, test evidence, and rollback conditions. Review FDCPA and CFPB Regulation F requirements with qualified counsel. Confirm that administrators can pause queued actions, investigate failures, and restore approved behavior without duplicating messages.
Ask vendors to demonstrate a realistic exception and explain where account restrictions are checked, how failed events are handled, and who can authorize a retry. Have compliance counsel review applicable FDCPA, Regulation F, TCPA, and state-specific debt collection requirements to ensure automated workflows maintain compliance across different jurisdictions.
At Aktos, the relevant question is how configurable collection workflows use current account information and handle exceptions. Agencies should test payment events, disputes, communication restrictions, and review permissions before relying on automated activity at scale.
Final Thoughts: Make Recovery Automation Testable
Debt recovery automation should make routine work more dependable, not make mistakes harder to stop. Before a new rule reaches live accounts, test its behavior when a consumer has disputed a balance, made a recent payment, opted out, or moved into a restricted status. Document who approved the change, what the tests proved, and how queued actions will be paused if something goes wrong. Those safeguards give teams room to automate more without treating every exception as an emergency.
In an Aktos demo, ask to walk through a proposed reminder-rule change, a failed test, and the steps needed to prevent an incorrect outbound action.
FAQs About Debt Recovery Automation
Q: How can agencies test automation without contacting consumers?
A: Use synthetic or de-identified test accounts, non-sending simulation modes, controlled staging systems, and mocked integrations that record intended actions rather than dispatching them.
Q: What triggers a workflow rollback?
A: Unintended contact, policy conflicts, incorrect account-state changes, material integration failures, or metrics that breach defined release thresholds should trigger a pause and review.