A software demonstration opens on aging invoices, accounts payable contacts, and a finance team’s cash flow dashboard. Those features may be useful for a creditor, but they do not prove the product can run a third-party collection agency. Accounts receivable management software has to be evaluated against the actual agency lifecycle: placements from multiple creditors, collector workflows, consumer communication restrictions, payments, disputes, remittances, and audit evidence.
An accounts receivable solution sold as accounts receivable automation software still needs an agency-specific evaluation. The goal is the correct action on the correct account, not simply faster invoice handling. This guide separates creditor finance requirements from third-party servicing so buyers can assess account history, client rules, and consumer treatment without confusing a shared software label with equivalent functionality.
Distinguish Creditor AR Tools From Third-Party Collection Software
Original-creditor AR automation software often focuses on invoice delivery, cash application, days sales outstanding (DSO), and order-to-cash operations. Credit management, credit approval, and revenue recognition belong to that finance context. Third-party agencies work accounts they do not necessarily own and must preserve client-specific placement instructions, settlement authority, consumer correspondence, and collection history. A modern agency platform must distinguish the client’s invoice record from the agency’s operational record.
A lender and a healthcare creditor may deliver very different placement schemas and client instructions. Standardize common fields without flattening those differences. Ask how the software stores original balances, adjustments, commissions, ownership details, recall instructions, and invoice documents, and how it prevents one client’s preferences from affecting another.
A creditor may keep its invoice records in accounting software such as QuickBooks, Xero, or FreshBooks, or in an ERP such as NetSuite or Sage Intacct. Some creditors may use AR Automation Software such as HighRadius, TreviPay, or Quadient A/R. Start the ERP integration review with a sample invoice, credit, and payment export. For example, check that an invoice created in QuickBooks retains its reference when placed with the agency and that a later Xero payment update cannot be applied to the wrong account. Establish which system supplies each balance before accepting live placements.
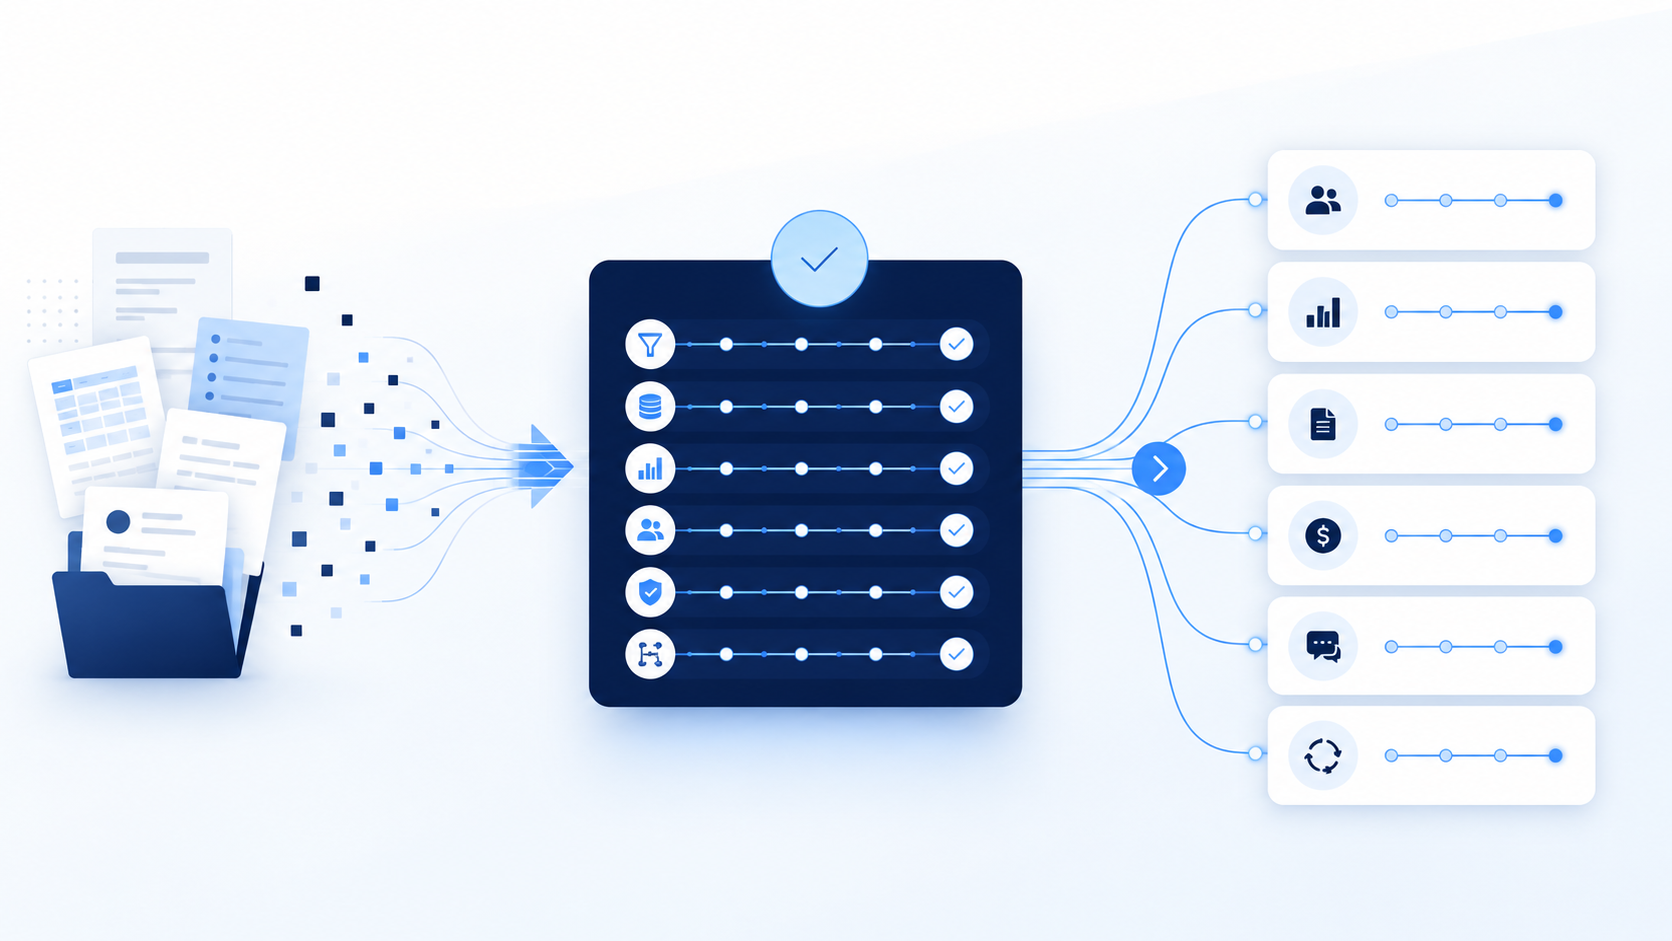
Evaluate the creditor-to-agency handoff through placement data, restrictions, and subsequent updates, not just invoice delivery, so the agency receives the account details and instructions needed to service each account correctly.
Configure Client Permissions, Remittances, and Portfolio Rules
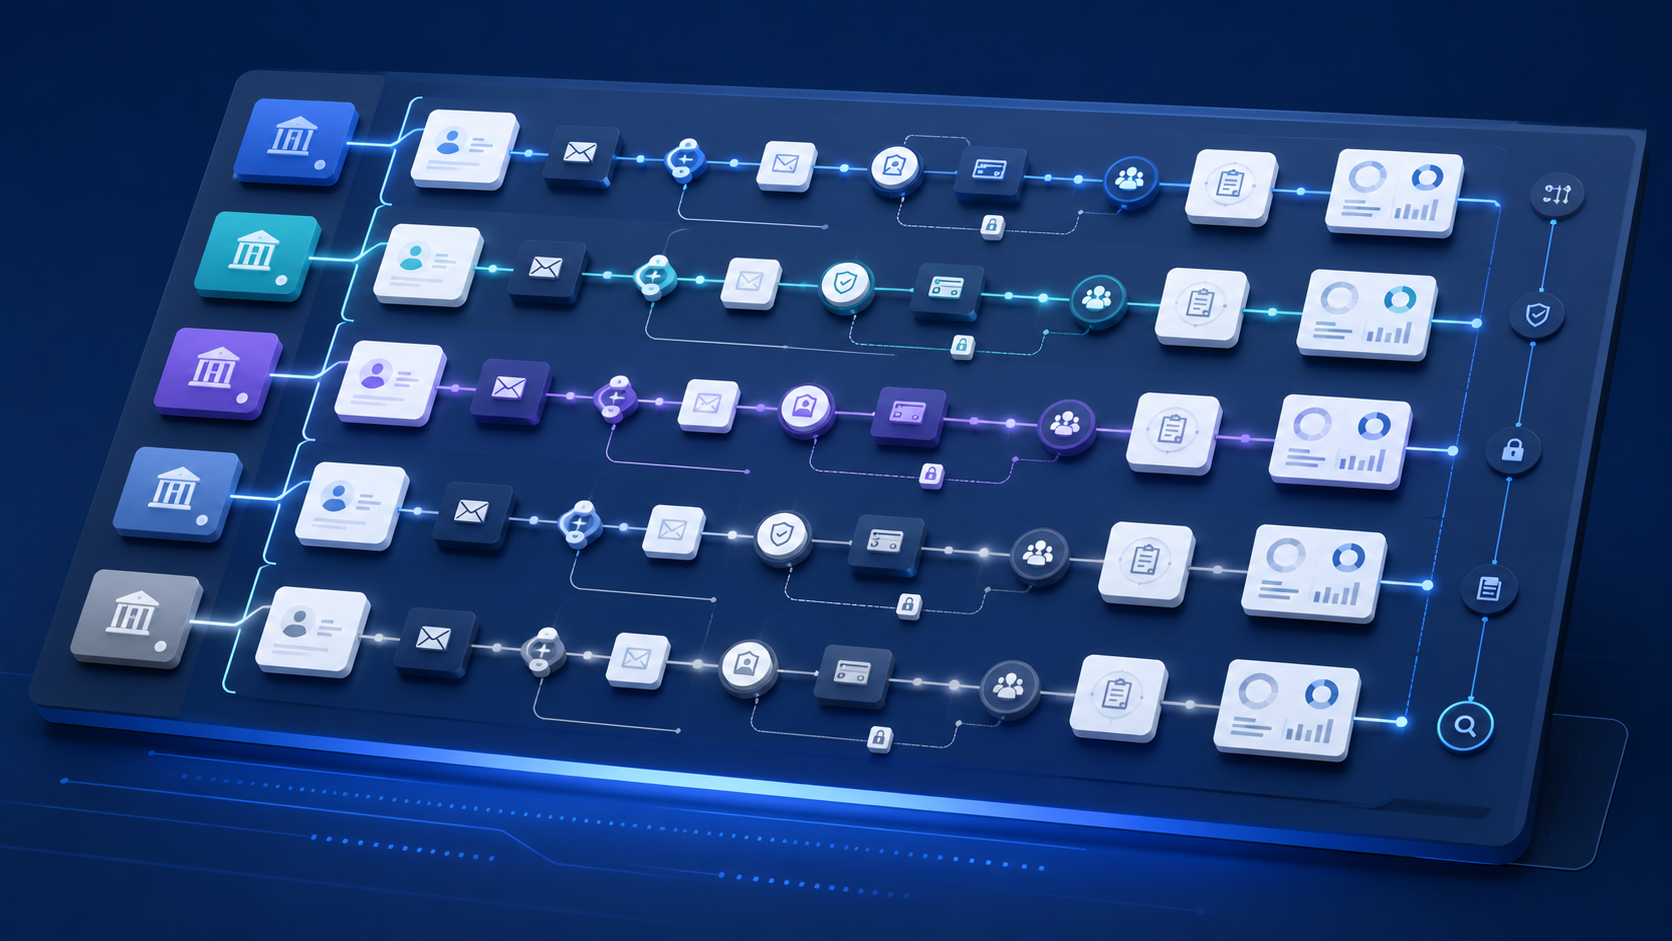
Permissions are central. A collector may be authorized for one client but not another; a client portal user should see their own portfolios, not a shared agency database. Settlement limits, approved message templates, legal handling, remittance schedules, and report definitions can vary by contract. Hard-coding those exceptions creates a maintenance problem as the agency grows.
Look for configurable client and portfolio rules tied to an auditable approval process. The platform should support placement acceptance, exception files, payment allocation, reporting, and requests for documentation without forcing teams into separate tools for each creditor. Client transparency improves when reports match the current system of record. Cash flow forecasting for working capital also needs clearly defined payment data.
Creditor-side accounts receivable platforms can add another step between accounting records and the agency. Billtrust and HighRadius offer cash application capabilities, while a Versapay customer payment portal may be where a creditor's customer pays or raises an invoice question. Map the proposed invoice-to-cash process before deciding what the agency must receive. An automated invoicing event, portal payment, or dispute resolution should carry the invoice reference, updated balance, and supporting detail needed to service the account.
Strong multi-client governance keeps permissions, approved rules, reporting definitions, and exceptions tied to the right creditor, making expansion possible without copying one client's operating assumptions into another portfolio.
Test Disputes, Payments, and Creditor-System Handoffs
Request demonstrations of dispute management, autopay, a credit card reversal, an ACH return, a consumer opt-out, and a settlement requiring approval. Test digital payment processing through a self-service portal. Track how data and permissions change at each step. Evaluate open APIs, error handling, search speed, secure exports, and implementation support—not just the attractive interface.
If your agency is replacing an older system, ask vendors to map historical statuses and audit trails into the new model. Pilot representative client portfolios before a general cutover. Accounts receivable automation software should make collection CRM work easier while giving compliance, finance, and client services a dependable common picture. When predictive analytics influences prioritization, ask which invoice and payment signals are used. Confirm that a changed prediction cannot override restrictions or approved client instructions before allowing it into operations.
For a creditor using Upflow, test how its collection workflow for overdue invoices hands off to the agency's workflow. When reviewing Quadient AR, formerly YayPay, confirm which product and export the proposal covers. In either case, trace a payment promise, partial credit, and unresolved dispute into the placed account. The handoff should prevent duplicate collections follow-ups while preserving the creditor's original invoice history.
Test enterprise debtor portals as part of the account journey, confirming that consumer payments, documents, and disputes update agency records and client visibility instead of remaining isolated self-service activity.
Pilot Agency-Specific Accounts Receivable Workflows
Assign someone to coordinate the creditor-to-agency handoff across operations, compliance, finance, and client services. Define the required invoice and account fields, who approves mapping changes, and who investigates failed transfers.
Test recurring invoices and recurring billing changes alongside disputed items. If a creditor records a payment in Billtrust or HighRadius after placement, confirm that the update reaches the agency before another reminder is sent. Then test a reversal: the revised balance should return to the correct account without clearing a dispute hold or communication restriction. Check how the creditor's payment portal and the agency's self-service portal display the same event.
Test an invoice dispute from the creditor's original record through the agency's hold, revised balance, and client report. Confirm that dunning stops when required, late payments post to the correct account, and automated dunning cannot reactivate a restricted item. Compare how each integration handles a duplicate invoice, partial credit, and disputed balance. These checks distinguish useful receivables functionality from an attractive dashboard that can still misclassify bad debt.
Track cash application errors, manual corrections, and time spent resolving missing updates. Days sales outstanding (DSO) and the Collection Effectiveness Index (CEI) help explain creditor performance, but a lower DSO does not show whether agency restrictions were applied correctly. For agency reporting, pair cash visibility with evidence of accurate balances, client instructions, and remittances. Better cash flow reporting should let finance distinguish collected funds from amounts still awaiting posting or allocation.
Review Multi-Client Controls and Integration Accountability
Use CFPB debt collection examination procedures to frame agency control questions with qualified counsel. Ask vendors to demonstrate client isolation, restricted actions, and application logging. Identify who approves creditor field mapping changes and investigates missing events before accepting a general assurance about AR automation.
Ask the integration provider to trace a disputed invoice from the creditor's record to the agency's hold and client report. Confirm that invoice references survive each transfer and that staff can reconcile balances across both systems.
Aktos is designed for third-party collection agency operations. Its configurable workflows and connected client records help agencies manage different creditor instructions, account restrictions, and reporting expectations.
Final Thoughts: Evaluate ARM Software Against Agency Work
Accounts receivable management software built for an internal finance team may be excellent at invoices and cash application yet leave third-party agencies struggling with creditor-specific instructions, settlement approvals, disputes, and remittances. Those differences matter when you serve multiple clients with different data formats and operating rules. A useful evaluation follows a placed account through a disputed invoice, payment, balance adjustment, and client report, checking whether cash flow is reconciled and the right people see accurate account information at each stage.
Bring two contrasting client workflows to a demo and assess how the platform could support their distinct permissions, reporting expectations, and exception handling.
FAQs About Agency Accounts Receivable Management Software
Q: What makes ARM software different for third-party agencies?
A: It must manage accounts on behalf of multiple creditors, with client-specific rules, permissions, dispute records, communication controls, remittances, and reporting.
Q: What should a multi-client platform support?
A: Separate client visibility, configurable permissions and workflows, placement validation, client reporting, payments, audit history, and secure data exchange.